Chapter 6 - The Price of Keeping His Project Alive
The bank's decision to suspend new advances did not make the outstanding money disappear.
Two days after my interview, Miriam called to explain that Tidewater Quay had been asked for revised cash-flow information. The lender was also reviewing the disputed guarantee separately. If Daniel couldn't demonstrate a realistic repayment plan, the company's trouble could grow quickly.
I asked if that meant the bank would come after me.
"It means we need to keep the two issues distinct," she said. "The business owes what it borrowed. Whether you owe anything under that paper is what we're challenging."
I repeated the distinction to myself. It was the first way I'd been able to think about the situation without feeling as though a single signature could erase everything I owned.
Daniel tried calling that afternoon. Then he texted that his staff were worried and he needed me to stop making accusations. I saved the messages and forwarded them to Miriam. I didn't reply.
The next morning, a courier delivered an envelope addressed to both of us. It contained updated account information from the lender. The papers showed that the project had not produced the expected repayment. A scheduled interest payment was overdue, and additional supporting documents were being requested from Daniel's company.
I took the envelope to Miriam unopened beyond what was necessary to identify its sender. There was no reason for me to review and handle complicated business notices alone anymore.
At her office, we discussed temporary arrangements for the house, our joint expenses, and what to do about our marriage. I had already decided I couldn't sleep beside Daniel while we waited for the bank to decide whether his deception would become my debt.
"You can separate those decisions," Miriam said. "You don't need to settle the marriage today to protect your position on the guarantee."
I appreciated that. I was tired of people presenting impossible choices as though they had to be made immediately.
I opened a new personal checking account for my earnings and arranged for my future deposits to go there. I didn't empty our joint account or hide marital property. Miriam had told me to preserve statements and keep paying ordinary shared obligations until we understood the legal issues.
That advice was less satisfying than cutting every tie in one dramatic afternoon. It was also what I needed.
Lauren agreed to give a formal statement through her own attorney. She described her bookkeeping role and the limits of her access to the company. She hadn't processed the loan application or handled the electronic signing. She had seen the completed papers because Daniel forwarded them after closing.
Her attorney provided copies of the emails Daniel had sent directly to her. One included the closing packet; another instructed her to record the fees. His assurance that I had approved the guarantee was preserved with its message history.
Lauren also acknowledged the affair. She and Daniel had begun seeing each other roughly six months before our anniversary. The guarantee was dated four months before the anniversary, during the same period in which I was asking why he kept coming home late.
I sat through that part of her statement because the timeline mattered. When it was over, I went outside and stood in the parking lot until my breathing slowed.
The betrayal and the financial misconduct were not the same act. But Daniel had been carrying both secrets into our home and telling me I was imagining the distance between us.
That evening, he arrived at the house at the time we'd agreed so he could collect documents relating to his personal property. I met him in the living room with a list prepared by Miriam. The list felt awkward and formal. So did everything else about seeing my husband now.
"This has gone too far," he said after looking at it.
"You have your clothes. You have your personal files. If you think something is missing, tell Miriam."
"I don't want to talk to a lawyer every time I need a shirt."
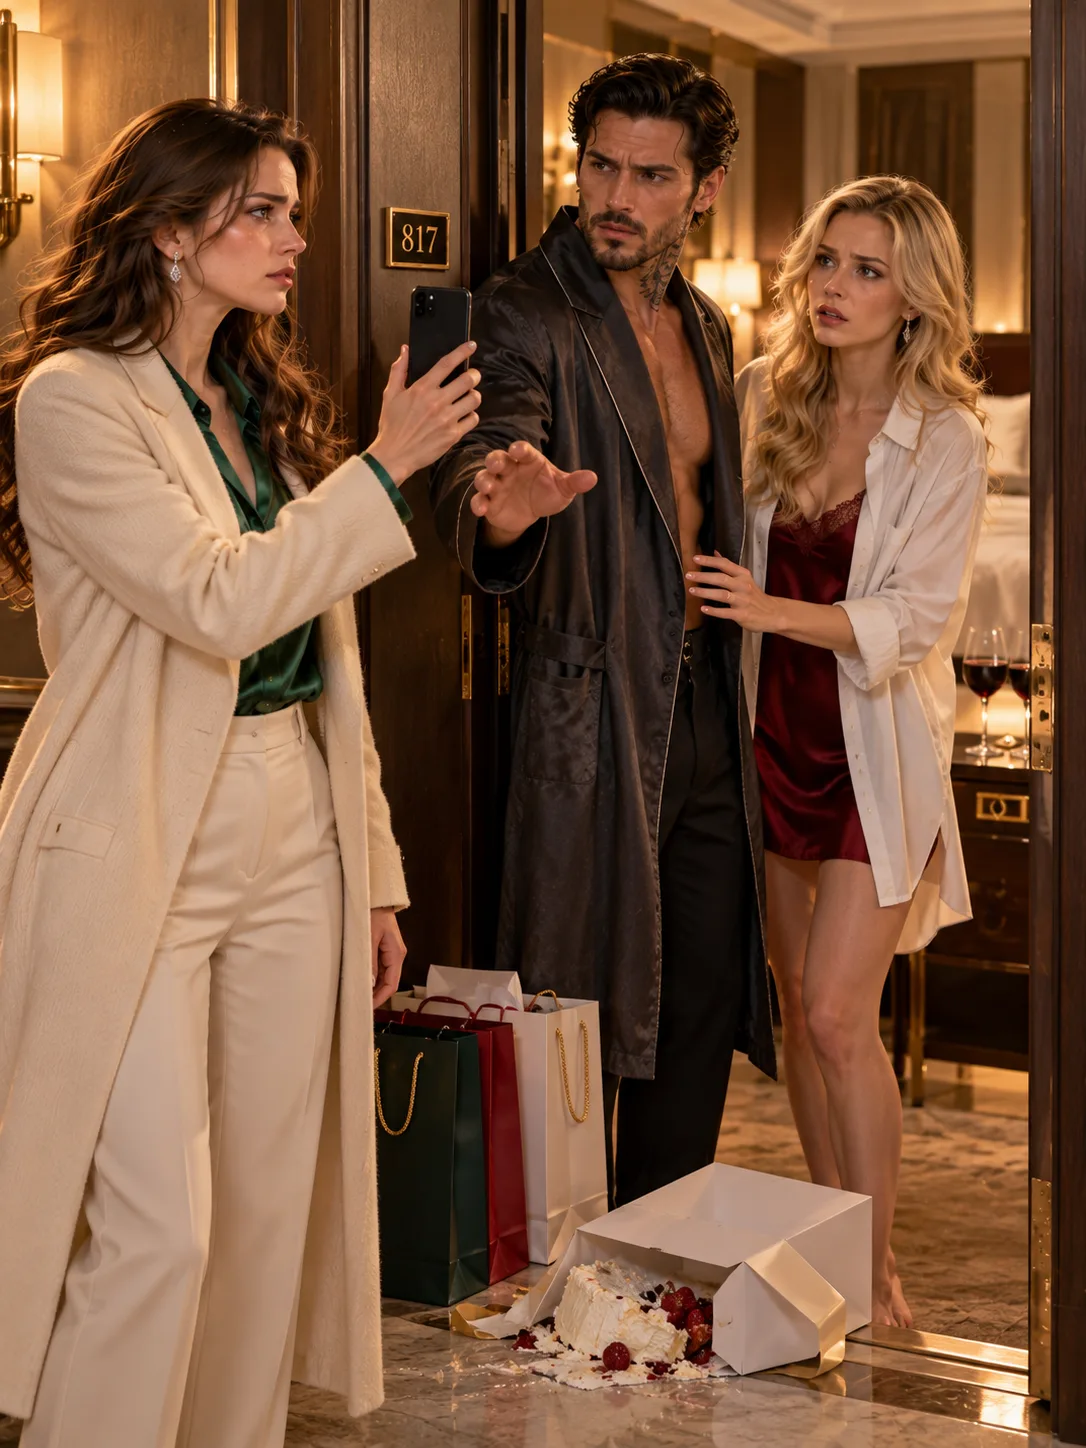
I looked at the shirt he was wearing. I thought of the white linen one Lauren had worn in Room 817, with the missing button I had promised to replace.
"Then you should have answered my questions before I needed a lawyer."
Daniel sat on the edge of the sofa. For the first time since the hotel, he looked tired rather than indignant.
He told me the Crescent Point project had run into trouble when renovation costs increased and a potential investor delayed a promised payment. Tidewater Quay needed short-term cash. A normal corporate guarantee hadn't satisfied the lender's terms, and Daniel had panicked.
"I had to close," he said. "If I lost that financing, I'd have lost everything I'd invested."
"So you used me."
"I thought I could repay it before you ever needed to know."
That was the first time he had described the risk as something he had intentionally hidden. He still hadn't admitted how my signature got onto the document.
"Did you copy my signature from the insurance form?" I asked.
His eyes moved toward the hallway.
"Daniel."
"I had copies of our paperwork," he said.
"That isn't an answer."
He stood. "I can't discuss every technical detail while you've got people building a case against me."
I wanted to tell him he had built it himself. Instead, I asked him to finish gathering his things and leave.
Before he went, he glanced again toward the anniversary gift bags, still beside the entry table. He reached for one handle, then stopped.
"I didn't want this to happen," he said.
"Which part?"
He couldn't answer.
The silence was more painful than I expected. I had spent twelve years recognizing when he was embarrassed or tired or afraid. The habits of knowing him didn't disappear just because I no longer trusted him.
After he left, I moved the bags to a closet. I couldn't bear to throw them away, but I couldn't keep seeing them every time I opened the front door.
Miriam called the following afternoon with news from the lender's financial review. The $312,000 already advanced hadn't been paid to me or transferred to our household accounts. It had moved through Tidewater Quay for Crescent Point's acquisition deposit, professional fees, and overdue project obligations.
That meant Daniel's story about trying to keep the project alive was consistent with the records available so far.
It did not make his conduct acceptable.
"Were there personal purchases?" I asked.
"Not in the summary the lender has provided," Miriam said. "We're not going to invent misuse where the accounting doesn't show it. The critical issue is the unauthorized guarantee."
I was surprised by how much that mattered to me. I didn't need Daniel to have stolen loan proceeds for a vacation with Lauren. What he had already done was enough.
A week later, the lender sent a written notice confirming that it would not demand payment from me while its fraud review was pending. It expressly reserved its legal position. Miriam warned that it was temporary.
Then a new message appeared in my inbox from a firm I'd never contacted, requesting confirmation of an upcoming borrower meeting. It had been copied to an address Daniel controlled and sent to mine because the lender now had my verified details.
Attached was a list of documents the company still owed. The last item was a signed statement confirming that all guarantors had been informed of material changes in the project.
My signature appeared nowhere on that page.
For the first time, the lender was asking for consent in words that required the person giving it to know what was happening.
I forwarded the request to Miriam and declined to sign anything.
That night, Daniel sent one final message.
If you won't help me, at least don't make the situation worse.
I read it once.
I thought about the months in which he'd told me not to worry while he was using my name to absorb the consequences of his decisions.
May you like
Then I replied with the only answer I still owed him.
Tell the truth.