Chapter 7 - What Daniel Told the Lender About Me
The lender's formal response arrived through Miriam's office ten days later.
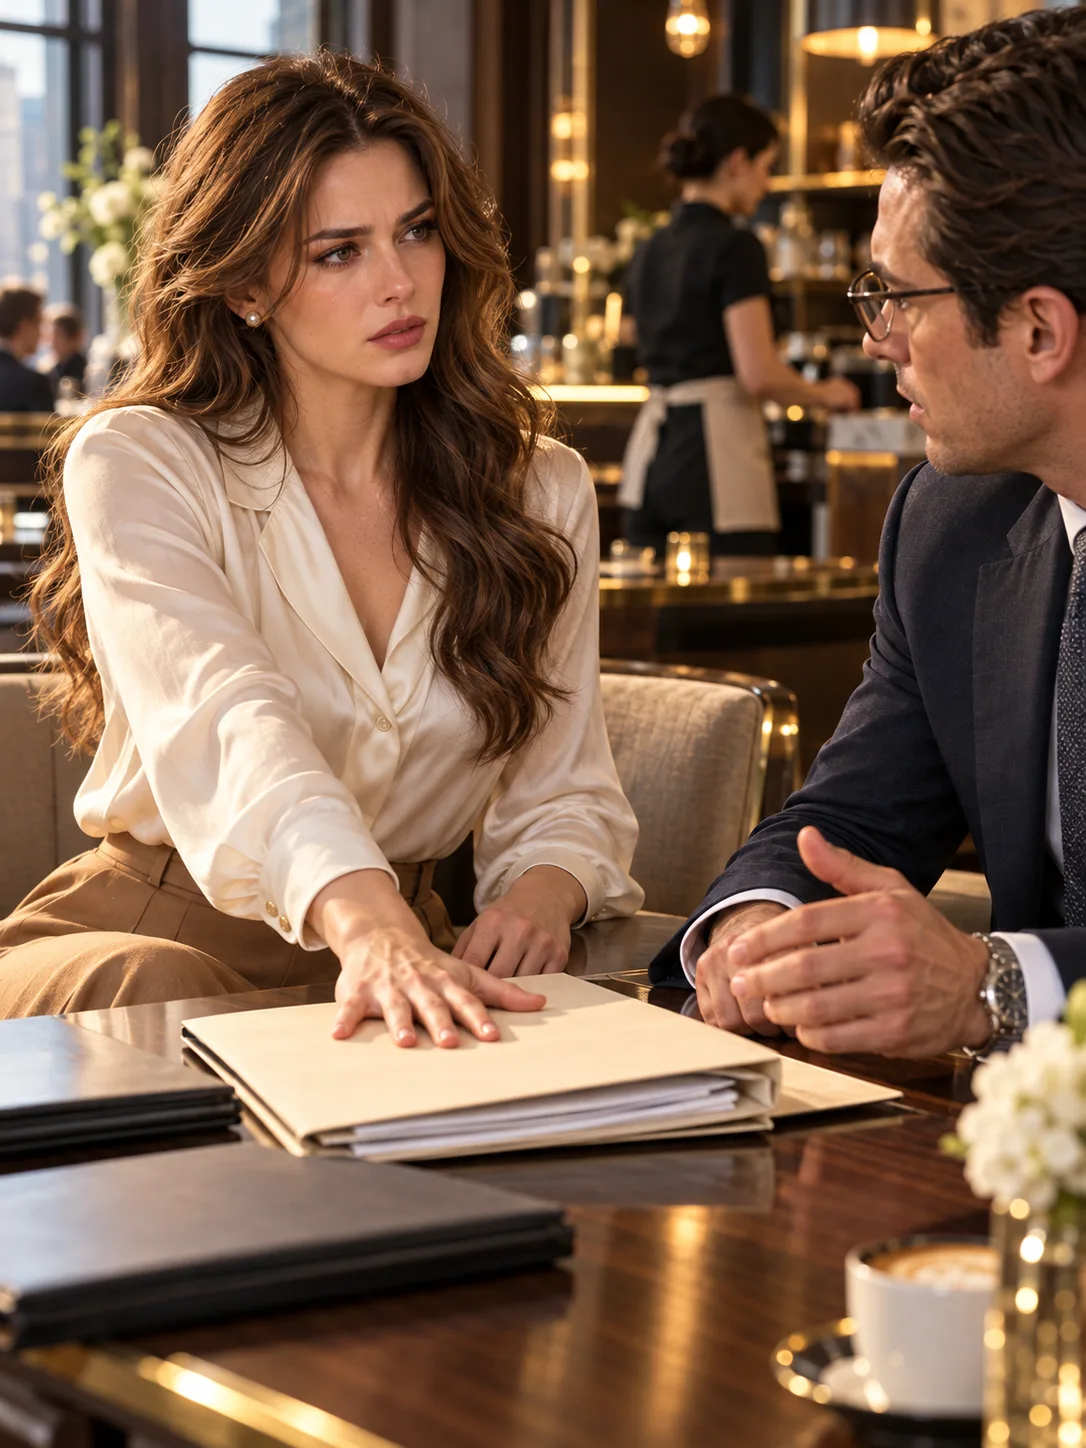
I was sitting in her conference room when she opened the packet. Outside the windows, traffic moved through an ordinary weekday. People were going to work, buying lunch, and answering calls. I remember noticing that because my life had begun revolving around a document I hadn't signed, while everyone else's continued uninterrupted.
Miriam arranged the records in chronological order.
The first was an application submitted by Tidewater Quay. Daniel was identified as its authorized representative. The requested facility limit was $460,000, secured by the company's business arrangements and supported by a separate personal guarantee listing me.
The second was a message from a bank employee asking how the lender could contact me to verify my agreement independently.
Daniel had replied from his business email.
My wife is with me during the closing process. Please use the secondary number below. It is the one we are using for these documents.
Beneath it was the number of his business phone.
For a few seconds, I couldn't look away from that message. Daniel hadn't merely allowed someone to enter the wrong contact details. He had supplied the number himself and said I was present.
I hadn't been.
The third record was the lender's signing audit. The document had been completed from the internet connection used by Tidewater Quay's office. The verification code had gone to Daniel's number and been entered shortly afterward. The purported signature appeared as an inserted image rather than a fresh handwritten mark created during the signing session.
Miriam laid the old homeowner-insurance form beside it.
The independent examiner had now completed a comparison. The report said the signature on the guarantee showed features consistent with a reproduction of the older signed image, including the same irregular hook beneath my name. It did not identify the person who performed the copying. That would require more evidence.
I didn't need an expert to tell me what my husband had wanted the lender to believe. His email already did that.
"He told them I was sitting beside him," I said.
"Yes."
"And he used his number."
"That's what the records show."
Miriam paused before continuing. "There's also a statement from the lender's employee. She says she relied on his representation. The compliance team is reviewing whether it should have required direct verification from you."
The bank had questions to answer too. I understood that. But those questions didn't change who had written the message.
"What happens now?" I asked.
"We'll send our position with this evidence, request written withdrawal of the guarantee, and pursue any protective court relief we need. We'll also separate the divorce case from the commercial dispute, while making sure they don't undermine each other."
She spoke carefully. No promises about instant justice. No triumphant declaration that the matter was finished.
When I got home, I found Daniel waiting in the driveway. He stood beside his car rather than coming to the door. I had told him not to arrive unannounced, but he said he needed five minutes. I stayed on the front steps and didn't invite him inside.
"The lender showed you my email," he said.
I hadn't told him that. Apparently, the bank was questioning him too.
"They did."
"I was trying to get the deal closed."
"You told them I was there."
Daniel looked across the street. "I thought it was a technical step."
"Was copying my signature a technical step?"
He closed his eyes.
For twelve years I had watched him try to find the right way to explain difficult things. I could recognize the pause before an answer he didn't want to give. This time I wasn't prepared to help him finish it.
"I used the insurance scan," he said finally. "I believed I could replace the guarantee before it mattered."
The admission came without drama.
He sounded tired. He sounded frightened. He also sounded as though he were still waiting for me to appreciate what he'd been trying to accomplish.
"You could have asked me," I said.
"You would have said no."
"Probably."
He looked at me then. Perhaps he expected me to apologize for that.
"That's why you didn't ask," I said. "You knew it was my decision, and you wanted a different answer."
Daniel said nothing.
I felt the last of my uncertainty leave. The bank had supplied a trail of technical evidence, but the part I would remember was his own explanation. He had known I might refuse, so he had removed me from the decision.
"And Lauren?" I asked.
He rubbed his face. "That was separate."
"You were seeing her while you used my name. Both things were happening when I asked why you were avoiding me."
"I didn't want to lose the business."
"You didn't want to tell me."
His eyes filled, but he didn't deny it.
I didn't know whether he regretted what he'd done or the fact that he could no longer hide it. At that moment, I wasn't interested in guessing.
"Please leave," I said.
He stood there a moment longer, then got into his car and drove away.
I wrote down our conversation as soon as I went inside. I had not recorded it, and Miriam had told me that a contemporaneous account could help preserve what I remembered, even if it wasn't proof by itself. I sent it to her. Then I sat quietly until I could make myself eat dinner.
The following morning, Lauren's attorney provided an additional email Daniel had sent weeks before our anniversary. It was the one telling her that I had approved the financing. Alongside the lender correspondence, it revealed the same pattern: Daniel had told different people I knew, without ever telling me.
Lauren's role in the affair remained exactly what it had been. She had not turned into an innocent bystander because she finally spoke up. But the loan records did not show that she created the guarantee, entered the verification code, or instructed the lender to use the wrong number.
I wanted the investigation to distinguish what each of us had actually done. Daniel had spent months collapsing those distinctions whenever it suited him. I wasn't going to do the same.
Miriam filed the initial papers seeking a declaration that I hadn't executed the guarantee and an order preventing enforcement against me during the dispute. She explained that the court would decide the immediate request based on evidence presented, not on the fact that I had been betrayed by my husband.
"The affair is why you discovered the problem," she said. "It isn't proof of the financial wrongdoing. The records are."
I appreciated her precision, even when I wished the whole mess could be settled by the simple fact that Daniel had lied.
That afternoon, we received written acknowledgment from the lender that it was reviewing rescission of the purported guarantee. Its commercial team would continue pursuing repayment from Tidewater Quay and any responsible parties, independently of my complaint.
Then Miriam told me something else.
The company was preparing to sell its interest in Crescent Point. The lender had asked for a repayment proposal using the proceeds. Daniel's business was not yet collapsing, but keeping it alive would require actual sacrifice from him.
I thought of the night he begged me not to hurt the project.
He had risked my name so he wouldn't have to risk all of his own assets.
Now the two things were finally being separated.
I went into the hallway and opened the closet where I'd put the anniversary gifts. Three bags stood exactly where I'd left them. Nothing about their contents had changed. I was the one who had changed.
My phone rang with Miriam's number.
"Claire," she said, "the hearing on your protective application has been scheduled. Daniel has been notified."
I closed the closet door.
May you like
For months he'd made decisions without allowing me into the room.
This time, we would both be there.