Chapter 3 - Thirty-Eight Calls and One Denial
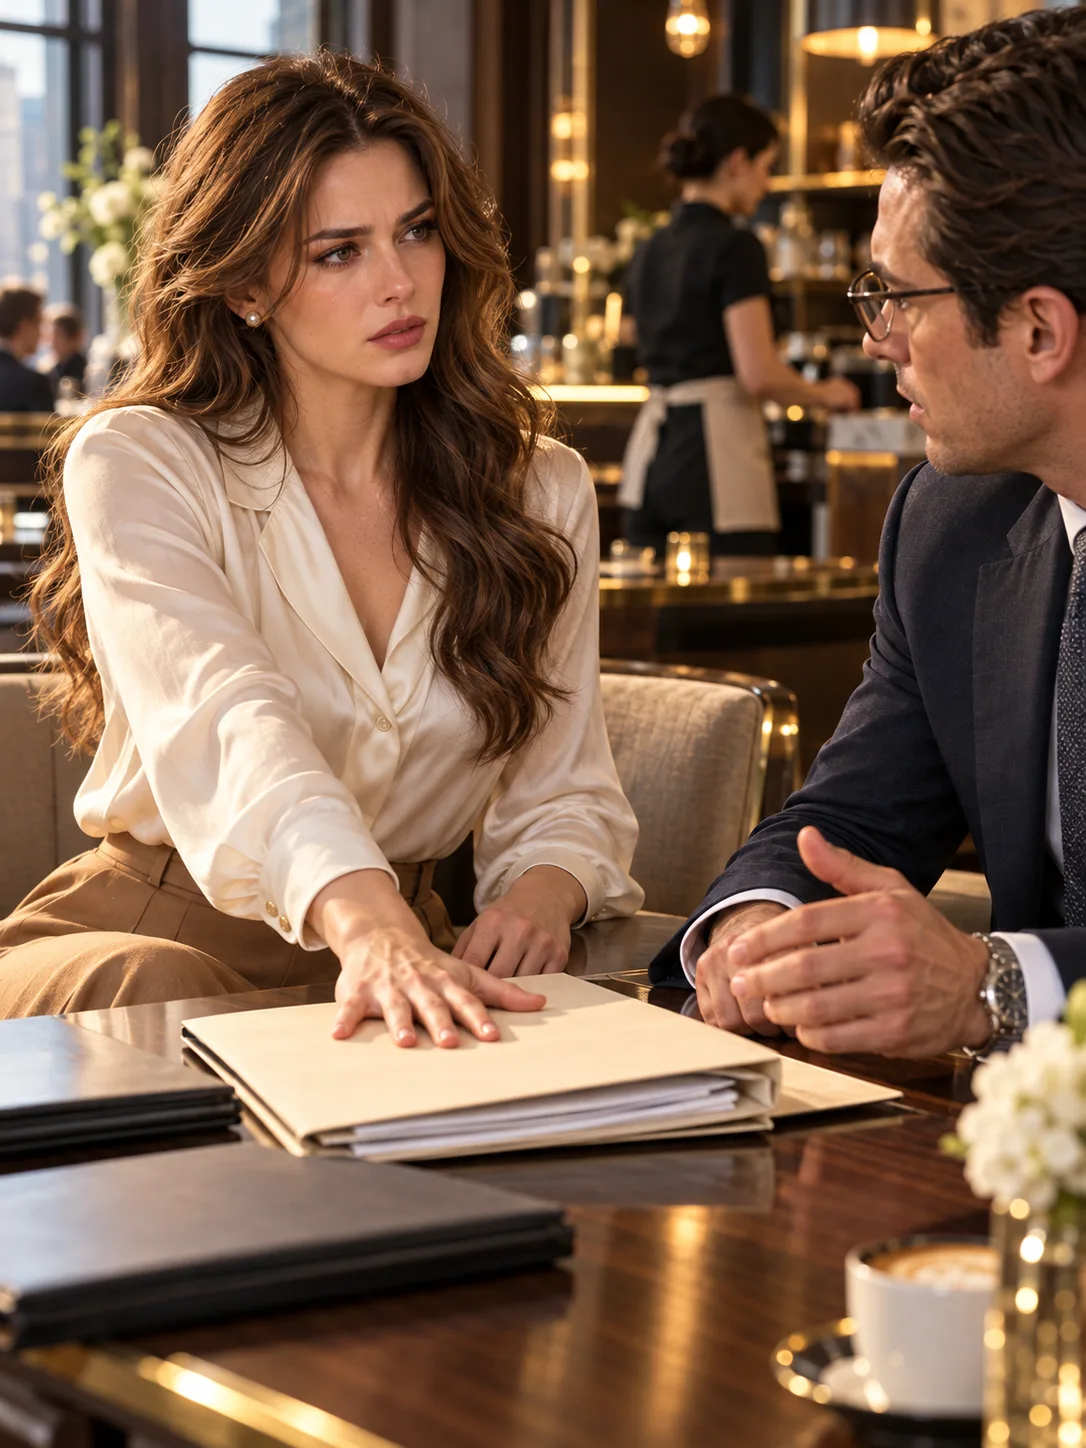
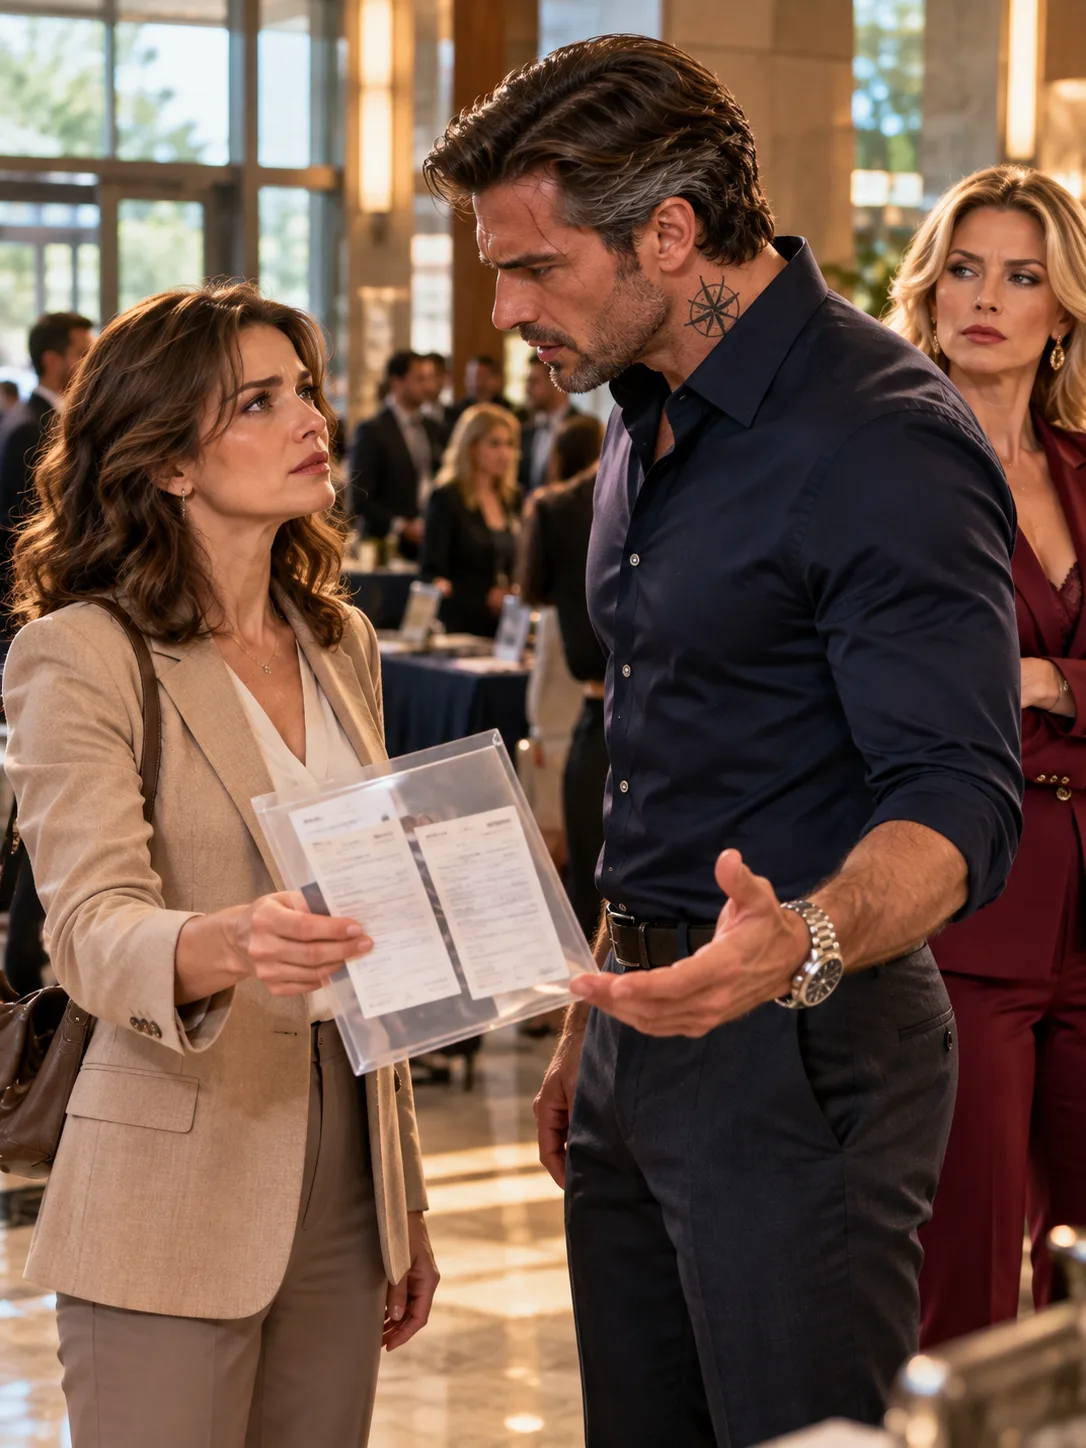
At the bank, Mom sat across from a fraud specialist with her blue cardigan buttoned neatly and her small hospital bag beside her chair. She had insisted on bringing the statement herself. The bag still held her medical instructions from the previous day, but she had added a notebook listing every withdrawal. I could see the effort it cost her to talk about money she had saved over a lifetime. I could also see that she intended to be heard.
My phone vibrated again. Gwen's thirty-ninth call arrived just as the specialist asked Mom to describe how she ordinarily made payments. I silenced it without answering. The thirty-eight unanswered calls from that morning already told me something was wrong; I did not need a shouted explanation before we had the records.
Mom described how she used the bank: pension deposits, ordinary household bills, pharmacy charges, and occasional checks. Three years ago she had given us the family loan that helped cover three months of mortgage payments. It had been meant as temporary help during a difficult period for Gwen's boutique, not as continuing financial support.
The specialist showed Mom an electronic copy of the payment record. The debits had originated through a commercial processor used by Gwen Hale Collections LLC. They were classified in the processor's system as payments for recurring 'household support services.' There were no invoices attached to the account record available to the bank. The bank had Mom's account information, a merchant identifier, and a claim by the originator that a valid authorization existed. That was not the same as proof that Mom had approved the arrangement.
"I don't buy household support services from my daughter-in-law," Mom said. "And I don't owe her a monthly fee for being part of the family."
The specialist explained the next steps without promising an instant refund. Mom signed a statement disputing the transfers, requested a new account, and arranged to move her direct deposits and legitimate bill payments safely. The bank would ask the merchant's payment processor for its records. It could investigate recent items promptly; older ones might require additional action. The blocked twenty-four-thousand-dollar request had not left her account.
We also learned that the debits were initiated using her checking-account and routing numbers. Those numbers had been printed on the check she used to help us with the mortgage three years earlier. We had no proof they came from that check, but Gwen had been in a position to see it. I remembered how casually I had handed household financial paperwork to my wife, believing our interests were the same.
Outside the branch, a voice message arrived. Gwen was no longer pretending that she simply wanted to know where I was.
"Brandon, answer me. The boutique payment didn't clear. I need to know what you've done."
I listened twice. She had connected my silence with her money problem without knowing what Mom and I had discussed at the hospital. Her choice of words suggested she expected the payment to clear. It did not prove she had personally arranged every withdrawal, but it made the need for answers more urgent.
I called her back with Mom's permission, using the quiet seating area outside the branch. "Why is your company taking money from my mother's account?" I asked.
For a second, Gwen said nothing. Then she spoke quickly. "Your mother offered to help. You know she's always helping."
"She says she didn't authorize these payments."
"She forgets things. You saw how confused she gets about appointments."
I looked across the lobby at Mom carefully checking the specialist's list of new account instructions. She had arrived at the hospital on time with her records in order. She had remembered our mortgage history more clearly than either of us. Gwen's attempt to make her age an argument against her honesty sickened me.
"The appointment wasn't confused," I said. "We almost missed it because you refused to let us use the car."
"Don't turn this into another lecture about your mother. The boutique has bills due."
There it was. She had not asked whether Mom was all right. She had not even asked if the bank had made a mistake. She wanted access to funds, and she wanted me to restore it.
"We'll discuss your business when we have independent records," I said. "Until then, do not contact her about this."
"You have no idea what you're doing to me," she snapped before ending the call.
Mom had heard only my side. I repeated what Gwen said, including the allegation that she was confused. I watched the muscles around Mom's mouth tighten. "I've lived long enough to know when somebody wants my silence," she replied. "But I will not let her decide whether I understand my own statement."
That afternoon, I met with an attorney named Rachel Mercer. I brought copies of the account entries, the bank case number, and the message Gwen had left. Rachel was direct about the limits of what we knew. Merchant records connected the debits to Gwen's company, but we still needed evidence of who submitted the payment instructions and how the money had been used. She advised us not to attempt to access Gwen's private accounts or remove documents from the boutique. The proper path was to preserve what we already held, notify the bank, and request records through authorized procedures.
She also urged me to separate the marital disagreement from the bank investigation. My marriage could fail without proving a financial crime. Mom could dispute unauthorized withdrawals regardless of whether Gwen and I stayed married. Keeping those issues clear would protect us from treating the evidence like a weapon in an argument.
When I returned home, Gwen was waiting beside the kitchen island. The SUV keys lay next to her designer handbag. She watched me enter and asked, with perfect calm, whether I had finally finished embarrassing her at the bank.
"Mom reported payments she didn't recognize," I said. "That's her right."
Gwen folded her arms. "Your mother volunteered that money. She knew I needed help after the slow season."
"Then we should be able to find the authorization," I answered. "The bank has asked for it."
She looked toward the window. The silence lasted long enough for me to recognize how unfamiliar it was. In most disagreements she would tell me what I had done wrong and wait for me to apologize. This time she did not offer a date, a document, or a single conversation in which Mom had agreed to fund her shop.
Instead, she said, "If you cared about our marriage, you would tell her to withdraw the complaint."
I took a breath. "If you cared about our marriage, you wouldn't ask me to make my mother ignore money leaving her account."
Gwen picked up her handbag and walked upstairs. I heard a drawer open, followed by the sharp sound of another one closing. When she returned, she held a printed page she claimed Mom had signed. Across the top were the words 'Family Support Authorization.' Beneath them was a copied signature that looked disturbingly like my mother's.
May you like
"There," Gwen said. "Now make her stop."
I looked at the paper without touching it. The signature resembled Mom's handwriting, but the language above it sounded nothing like anything she would have agreed to. The document was dated nine months earlier, one month after the withdrawals had already begun.