Chapter 4 - A Signature Dated Too Late
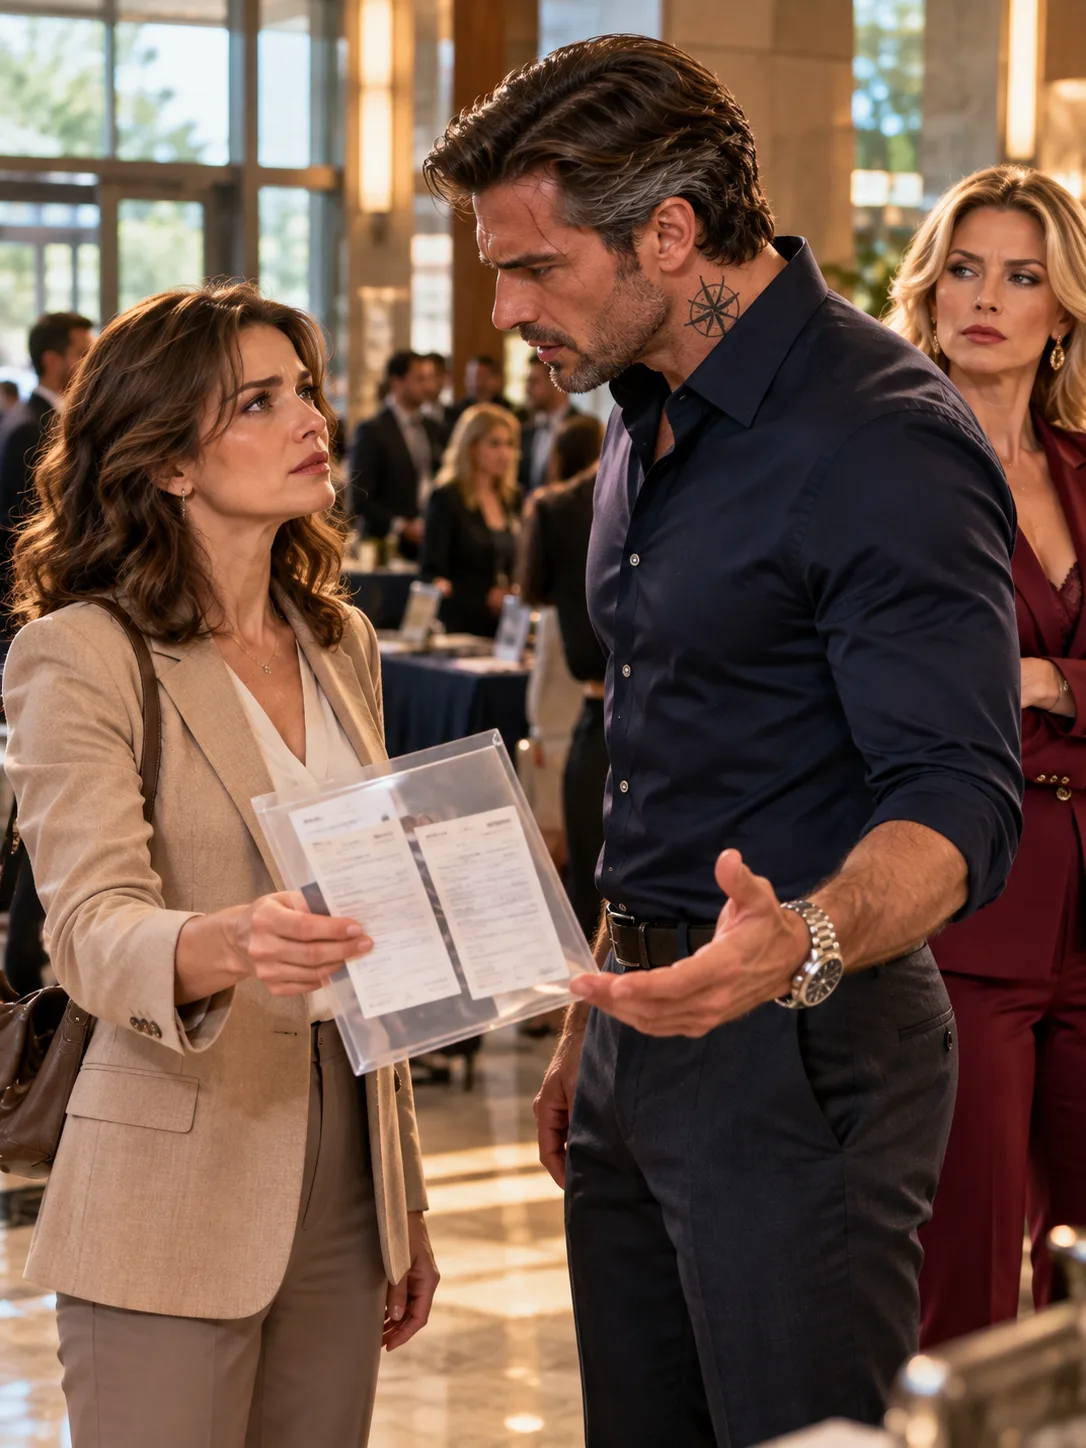
I asked Gwen why the authorization was dated after the first withdrawal. Her eyes moved from the page to me, then back again. She said the first month had been an advance against a family agreement. That explanation might have deserved investigation if it had been accompanied by a clear account of who had agreed, when, and for what purpose. Instead, Gwen kept insisting that my mother should be grateful she had a family willing to help her.
"Help her with what?" I asked. "These payments went to your boutique."
"The boutique supports our household," she answered. "You're acting like I spent the money on strangers."
I wanted to remind her of the hospital parking fee, of the car keys she had refused to hand over, and of the banana bread Mom had baked the night before her appointment. But Rachel's advice returned to me: do not confuse an argument with evidence. I told Gwen to keep the document available for her attorney and the bank. I photographed the page only after she placed it on our shared kitchen table and told me to inspect it. I did not take the original.
She seemed relieved when I stopped asking questions. That frightened me more than her anger. She believed that producing a signature, whatever its history, ought to finish the matter. She expected Mom and me to accept a piece of paper without examining when it appeared or what it actually authorized.
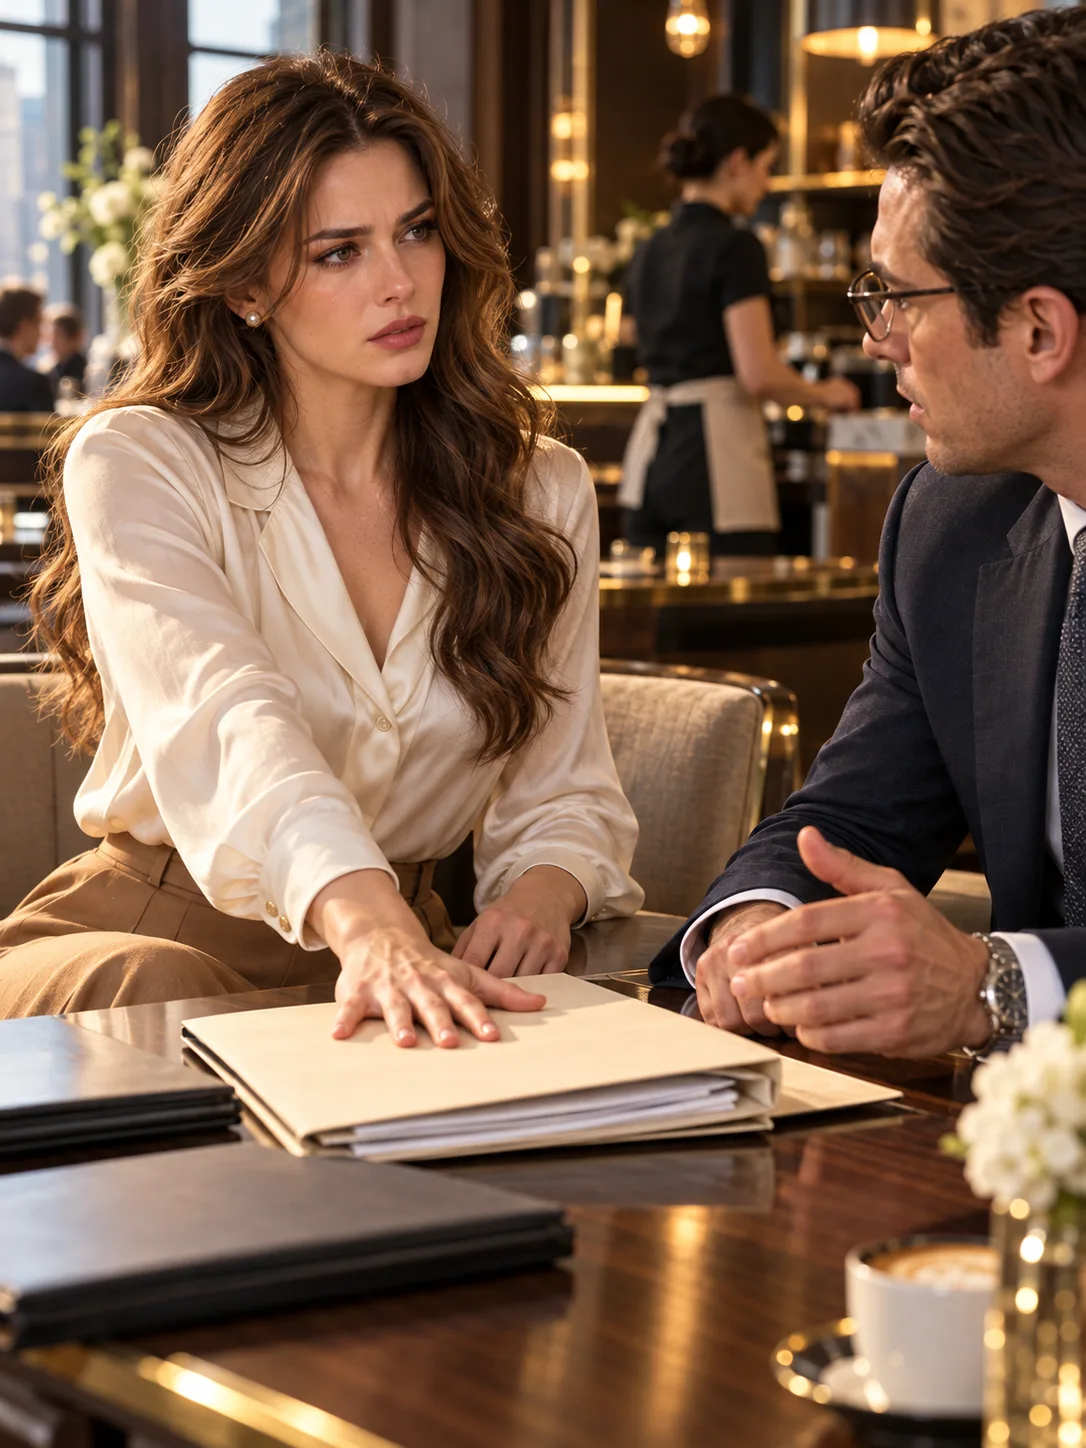
The following morning, I took my copy to Rachel. She pointed out that the form described monthly payments of eighteen hundred and fifty dollars but did not mention the twenty-four-thousand-dollar request. It also bore no bank stamp, witness signature, or identifiable explanation of how Mom had received it. Those omissions did not automatically make it fraudulent. They made the paper inadequate to settle the dispute.
Mom joined us later, carrying an old folder of important household documents. Rachel placed the copied authorization before her. I sat close enough to see her reaction but did not speak for her.
"That's my signature," Mom said slowly. "Or a copy of it. But I've never seen that form."
She examined the date. On the day printed above the signature, she had been at a follow-up medical visit with me, and then at home. She remembered it because we had stopped to buy groceries afterward. It would have been easy to take that memory as proof she could not have signed anything that day, but Rachel cautioned us against assumptions. The stronger point was that Mom denied authorizing the arrangement, and the merchant would need to provide its actual records.
Mom opened her folder and drew out a photocopy of the old family-loan agreement. Three years ago she had signed that note at our kitchen table. The family loan carried no interest and had never been intended to entitle anyone to future withdrawals. I remembered Gwen insisting that we put the arrangement in writing so there would be no confusion about whether the money was a gift. I had admired that caution at the time.
Rachel placed the old signature and the one on Gwen's form side by side. They appeared strikingly similar, down to a slight hesitation in one letter. A copied signature was a possibility, not yet a conclusion. Rachel suggested that a document examiner could compare the originals if the case required it.
"I don't need someone to tell me I didn't agree to pay a boutique every month," Mom said. Then she looked at me. "But I understand why the rest of the world needs proof."
There was dignity in the way she said it, and sorrow too. My mother had helped us when our mortgage was at risk. Now she was sitting in a lawyer's office asking strangers to establish that generosity had not become permanent permission.
That afternoon, Gwen called my workplace. When I did not agree to discuss the dispute during business hours, she sent a message saying that Mom was making up the story to turn me against her. She warned that people would hear how much stress I had caused at home. Before the day ended, two acquaintances had already contacted me about rumors that I was refusing to support my wife through a cash-flow problem.
I wanted to defend myself to everyone. Rachel advised me to resist publishing financial allegations while the bank investigated. I told the people who asked that a private account dispute was being handled through the proper channels. I would not expose Mom's banking history to win a social argument.
Instead, I visited Mom after work. She was at her dining table with a cup of tea, writing down questions for the bank. She had also set out a piece of the banana bread she had baked for Gwen. Seeing it there reminded me how ordinary our family life had seemed until the hospital appointment forced us to examine it.
"I don't want my money back if getting it destroys your life," she said.
"You don't have to choose between your savings and my marriage," I replied. "Neither should have been put against the other."
Mom looked at me for a long moment. "I don't want you to lose yourself trying to keep everyone happy," she said. "You were a kind boy. You grew into a kind man. Just be certain your kindness includes you."
The bank called the following morning with an update. The processor had received our dispute and was gathering the merchant's supporting material. The twenty-four-thousand-dollar request remained blocked. The recurring debit instruction had been created online ten months earlier, shortly before the first withdrawal, not on the date of Gwen's printed authorization.
There was more. The processor's record listed the person who opened the merchant payment request as Gwen Hale, using the business's verified account. That did not tell us whether my mother had authorized it, but it placed responsibility for providing that authorization squarely with my wife.
May you like
I thought of Gwen standing at our kitchen island with a paper dated after the money started moving. Whatever else we learned, one thing was already clear: she had supplied a document whose timeline contradicted the payment record.
And if the form was supposed to explain the withdrawals, we needed to learn why it existed at all.